Small business health insurance for your team


When you run a small business, every person matters. If a key member of staff is waiting for a diagnosis or treatment, it can affect your customers, your workload and the rest of your team. Small business health insurance gives your employees a potentially quicker route to specialist consultations, scans and treatment, while they stay fully entitled to NHS care.

Morehealth is an independent, FCA regulated health insurance broker. We compare small business health insurance from leading UK insurers, explain the differences clearly and help you set up a scheme that suits your team and your budget. Our advice is free to your business. We are paid a commission by the insurer you choose, and this is not added to your premium.


Corporate Health Insurance Plan For Small Business Team
  • FCA Regulated

  • Independent Broker

  • 15+ Years Experience

  • UK-Based Advisers

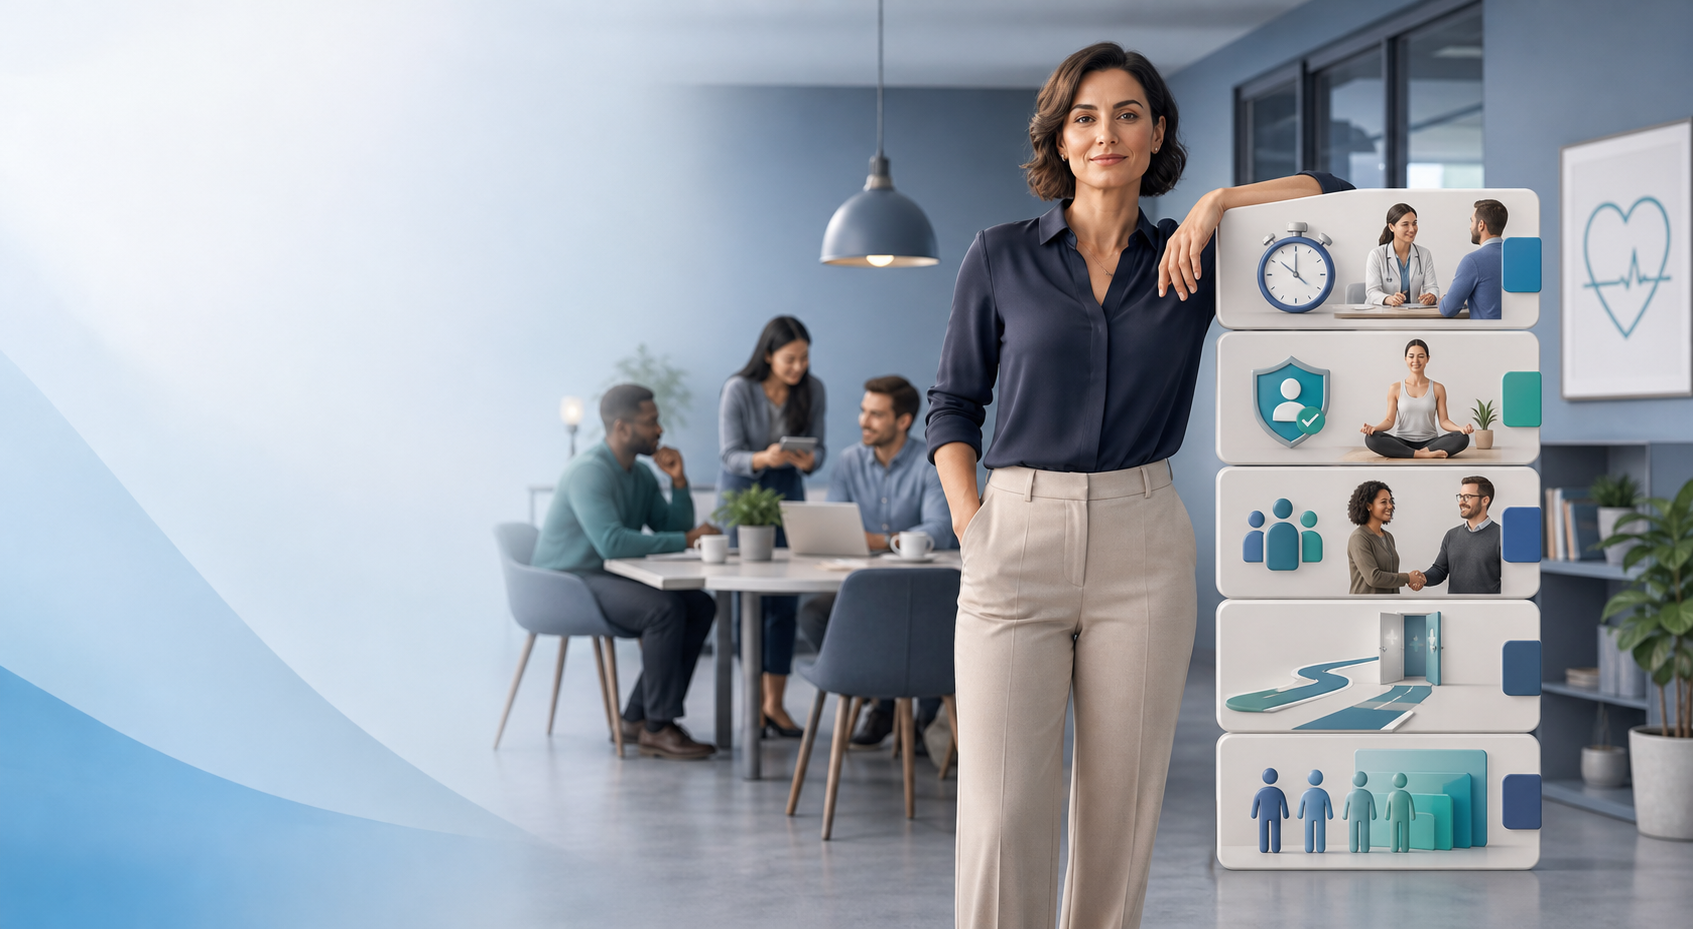
Small Business Private Medical Insurance Benefits Chart

Why small businesses choose private medical insurance

Company health cover is no longer just for large employers. Many small businesses introduce it to look after their people, reduce the disruption caused by long absences and offer a benefit that stands out when recruiting. With NHS waiting times still a concern for many employees, private cover provides an additional route for eligible consultations, scans and treatment.


Businesses often introduce private medical insurance to provide:

  • Faster Access To Consultations And Diagnostic Tests
  • Support For Employee Wellbeing And Confidence
  • A Valued Benefit For Recruitment And Retention
  • Quicker Treatment Routes For Directors And Key People
  • Fair, Consistent Cover Through Structured Levels

Cover built around the way your business works

There is no single scheme that suits every small business. Depending on the insurer, your options can include:

  • A Single Level Of Cover For All Employees
  • Tiered Cover For Directors, Managers And Staff
  • Director Only Private Medical Insurance
  • Adjustable Excess Levels To Help Manage Premiums
  • Optional Benefits Such As Enhanced Outpatient Or Mental Health Cover

Many schemes also allow employees to add partners or children at their own cost, depending on the insurer and scheme rules. Our guide to health insurance options explains the main choices in more detail.

How we set up your scheme

We start by understanding your team, including employee numbers, locations, budget and the type of cover you want to provide. We then compare leading UK health insurance providers, including Bupa, AXA, Aviva, Vitality and WPA, focusing on practical differences such as hospital access, benefit limits and pricing structures.
We present a clear recommendation and explain why it suits your business, alongside any alternatives worth considering. If you go ahead, we guide you through onboarding, paperwork and employee communications, and help with scheme rules, joining windows and adding family members.
As your company grows, we can help you adjust employee eligibility, introduce additional levels of cover or add optional benefits
.

Already have a business scheme?

Each year we review your scheme at renewal and compare it with the wider market. If another insurer could offer improved value or benefits, we explain those options clearly and how existing underwriting may be protected. If staying with your current provider is the best option, we support you through the renewal. Start with a free health insurance check.
Why choose Morehealth

  • FCA Regulated (FCA Number 815733)
  • Independent Broker Comparing Leading UK Insurers
  • More Than 15 Years Of Experience
  • UK Based Advisers
  • Member Of The Association Of Medical Insurance Intermediaries (AMII)
  • Advice For Individuals And Businesses Across The UK

Speak to a friendly adviser on 0800 028 5540, message us on WhatsApp or contact us online. There is no pressure to proceed.

We Compare Leading UK Providers

 We work with all major health insurance providers to find your perfect match 

Stop paying too much for health insurance

Check If You Could Save

Already have health insurance? We’ll review your current policy and help you understand whether it’s still right for you.

Request a Free Health Insurance Check

Frequently Asked Questions


How many employees do we need for small business health insurance?

Most insurers need at least 2 people on a business policy, although some will set up a plan for a single member, such as a sole company director. Schemes can grow as you take on staff. The minimum varies by insurer, so we check the current criteria for your business.

Director-only cover is a common starting point. As an illustrative example, a company with 2 directors might start with cover for both of them. You can later extend the scheme to employees, either at the same level or a different one. Directors are generally treated like employees for tax purposes.

If you're a sole trader with no company or employees, a business scheme usually isn't available. A personal policy is the more suitable route, and our page on self-employed health insurance explains the options.

Is small business health insurance worth it, and is it a legal requirement?

There's no legal requirement in the UK for employers to provide private medical insurance, so it's a voluntary benefit unless your employment contracts promise it. Whether it's worth it depends on your goals and budget. Many small businesses use it to support wellbeing and to attract and keep staff, but it adds a cost.

Cover gives employees a route to private consultations, scans and treatment for eligible acute conditions, while the NHS remains available to them. It isn't sick pay, and it doesn't cover emergencies or the ongoing management of chronic conditions.

Setting clear eligibility rules from the start makes a scheme easier to run. For example, you might decide that cover begins after a probation period, or that only certain roles qualify. It's worth taking HR or employment advice so the rules are applied fairly.

Some businesses start with directors or key people and extend the scheme as they grow. Our guide to NHS waiting times explains why delays are a common reason employers consider cover. We'll tell you honestly if a scheme is unlikely to offer good value for your team.

How much does small business health insurance cost?

There's no fixed price. Premiums are usually worked out per person, so the cost depends on how many people are covered, their ages and locations, the level of cover, hospital list, excess and underwriting method. Because insurers price differently, we can't give an accurate figure until we know who you'd like to insure.

Premiums can also change at renewal, for example when your team's ages change, people join or leave, or the scheme's claims history develops.

There are practical ways to adjust a scheme to your budget, although each has a trade-off:

  • A Higher Excess Per Person: Employees pay more when they claim
  • A Lower Outpatient Limit: Consultations and tests may be capped
  • A Targeted Hospital List: Fewer hospitals are available
  • Tiered Cover: Different levels for different groups, such as directors and staff

Our guide to how much private medical insurance costs explains the wider pricing factors.

Is small business health insurance tax deductible?

A limited company can usually treat the premiums as a business expense, but cover is normally a taxable benefit in kind for the employees or directors who receive it. The company usually pays Class 1A National Insurance, and employees pay income tax on the value. Your accountant should confirm how this applies to you.

HMRC says that when an employer arranges and pays the provider directly for medical insurance that isn't exempt, the benefit must be reported on form P11D and Class 1A National Insurance is payable on its value. You can read more in HMRC's guidance on what to report and pay for medical insurance.

The tax treatment can differ if an employee arranges the policy and you pay the provider, or if you reimburse their costs. It's worth setting the scheme up in the right way from the start.

We can explain how different scheme designs might affect the overall cost, but we don't give tax advice, and rules can change.

How does underwriting work for a small team?

Smaller schemes usually use moratorium or full medical underwriting, which means recent conditions may be excluded. Larger schemes may qualify for medical history disregarded underwriting, which covers pre-existing conditions without health questionnaires, depending on the insurer. Business cover is designed for acute conditions, and chronic conditions are not covered for ongoing management.

With moratorium underwriting, anything an employee has had symptoms, treatment or advice for in the 5 years before joining is not covered for the first 2 years. After that, it may become eligible if they've been free of symptoms, treatment and advice for 2 continuous years.

With full medical underwriting, each employee completes a health questionnaire and the insurer confirms any exclusions at the start.

Generally, chronic conditions are not covered. Some policies may cover the initial diagnosis and treatment of a flare-up, but ongoing management of a chronic condition is not covered, whichever underwriting you choose. Our guide to health insurance underwriting explains each option in more detail.

Can employees add family members or contribute to the cost?

Often, yes. Many schemes let employees add partners and children, usually at their own cost, depending on the insurer and scheme rules. Some businesses also ask employees to contribute towards the premium. How you structure this affects both cost and tax, so it's worth deciding before you set up the scheme.

Each person's medical history is considered individually under the scheme's underwriting, so one family member's condition doesn't affect what is covered for anyone else. Joining windows may apply, so it's best to confirm when people can be added.

When someone leaves, they can often move to an individual policy, and in some cases their existing underwriting can carry across. We can guide leavers through their options before their cover ends. You can find out more about individual health insurance.

Is a health cash plan an alternative to small business health insurance?

A health cash plan is a different product. It pays back set amounts towards everyday costs such as dental, optical and physiotherapy, whereas private medical insurance pays for eligible private diagnosis and treatment of acute conditions. Some businesses consider both, but a cash plan isn't a substitute for medical insurance.

Cash plan benefits are usually capped at modest amounts and are designed for routine costs rather than major treatment, so the two can suit different needs. Check each plan's limits and terms carefully before you decide.

Our service compares private medical insurance. If you're unsure which type of product suits your business, tell us what you want the benefit to achieve and we can explain how private medical insurance would or wouldn't meet that need.

How do we choose an insurer, and can we switch later?

Compare insurers on the details of cover, not price alone: hospital lists, outpatient limits, excess, cancer cover and underwriting. No insurer is best for every business. You can usually switch at renewal, and in many cases your existing underwriting can transfer, subject to the new insurer's acceptance.

Finding the right private medical insurance isn't just about the lowest premium. At Morehealth, we help you compare insurance options and understand the differences in price, hospital networks, excesses and levels of cover. Our aim is to help you find a policy that suits your needs and budget, without compromising on the benefits that matter most to you. The cheapest policy isn't necessarily the most suitable, and savings are not guaranteed.

We compare the leading UK health insurance providers so you can see the real differences. If you already have a scheme, start a few weeks before renewal so there's no gap in cover. We explain how we review or switch an existing policy on our website.

How do we set up a scheme and get a quote?

Tell us how many people you'd like to cover, their dates of birth and postcodes, and your budget. If you already have a scheme, send your renewal date and documents. We compare insurers, recommend an option and help with onboarding. We don't show instant online prices, because an estimate that ignores your details can be misleading.

You can request a business health insurance quote, call us on 0800 028 5540 or message us on WhatsApp. Once you've chosen a policy, the underwriting terms are confirmed before cover starts, and we review the scheme with you each year at renewal.

Our advice is free. If you take out a policy, we receive commission from the insurer you choose, and this commission is not added to your premium. There's no obligation to proceed.

Morehealth Limited is authorised and regulated by the Financial Conduct Authority (FCA), firm reference number 815733. We're also a member of AMII, the Association of Medical Insurers and Intermediaries